AWAKEN Sanctuary
A proven Amazonian conservation-tourism lodge, restarting.
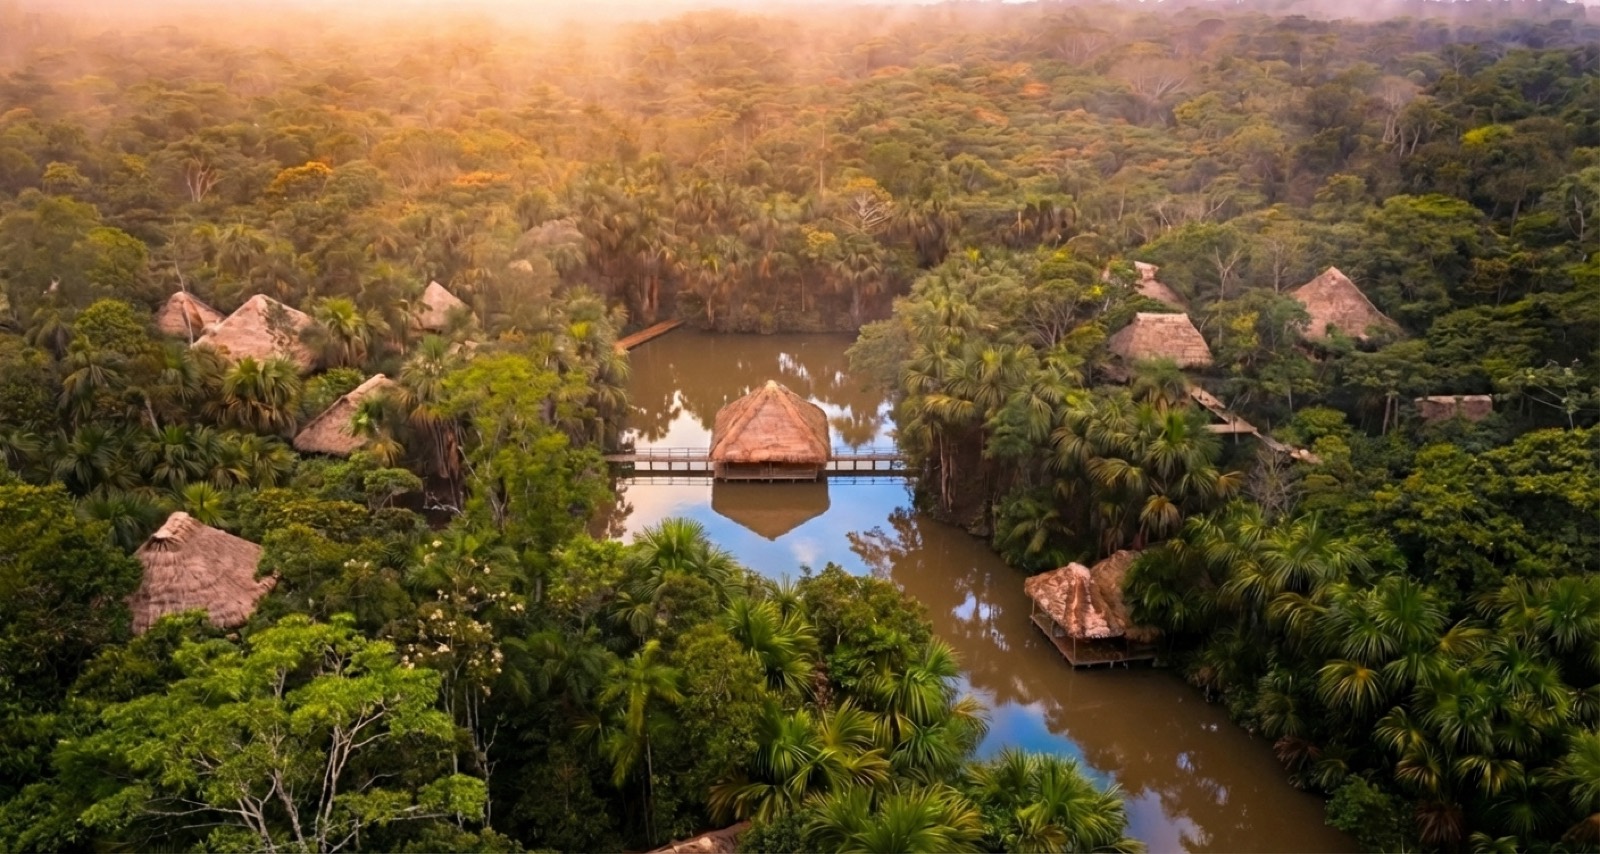
There is a line in the Amazon where primary rainforest ends and cleared land begins, and every year that line moves inward as frontier families clear and burn the forest plot by plot. AWAKEN Sanctuary sits on that line by design — built to answer one question in practice rather than on paper: how to actually stop the destruction at the frontier, not through fines or activism but by making a protected, living forest worth more than a cleared one.
It is not a concept. It is a built, operating asset: a private lodge of 35 villas on 24 hectares of titled rainforest, 15 km from Iquitos, constructed between 2021 and 2024 for about $2.62M by 45 investors, and proven in the market — 96+ guests from 15+ countries — before extreme weather forced it to close. The conservation idea is already proven on the ground too: once logging and hunting stopped, wildlife returned over the following years, from birds and caimans to breeding sloths and ocelots.
The raise — disciplined by design
- Tranche 1 — Equity ~$700k (mandatory). Reopens the property, funds year-one operation and marketing, and reaches profitability. This is the only capital the business strictly needs.
- Tranche 2 — Convertible standby up to $1.64M. Committed for conservation and growth, drawn only if operating cash is short. In the base model only ~$505k is ever called; operations self-fund the rest.
- Total committed $2.34M. Entry is priced at the value of the damaged asset today (~$2.62M pre-money, ~21% for the equity), not on the post-restart upside.
The shape (management estimate)
- Stabilized 2031: ~$4.74M revenue, ~$1.97M EBITDA, a 41.5% margin — premium pricing on a low Peruvian cost base. Loss-making by design in 2026–27, profitable from 2028.
- Returns on the $700k equity: ~4.2× MOIC, ~24% IRR (pro-forma, after the convertible converts).
- Downside (occupancy −30%, rates −15%, costs +15%) still holds a ~23% margin.
Why it is rare
The hard, slow, expensive part is already done and already worked: land titled and registered with SUNARP, lodge built, corporate and tax structure (Ley 27037, 5% income tax, in force through 2048) in place, and demand validated at premium prices. What remains is a disciplined restart.
Forward-looking figures are management estimates. Confidential.